
Whether you’ve stopped working or are still going strong, now may be a good time to think about how your super can support the next stage of your life.
We also have some social and health tips for you to consider – because a fulfilling retirement isn’t just about your finances.
Your super options after 60
Know where you stand
Download the Retirement Readiness checklist now
Housekeeping tips
Account-Based Pension
Keep your super in accumulation
Transition to retirement
Boost your retirement savings
Choosing the right investment option
It’s also a great time to do some housekeeping.
- Check you have nominated your beneficiary(s). And, even if you have, it’s important you make sure that the information is up to date. You can make a beneficiary nomination within the member app or complete this form. You also have the option of making a binding death benefit nomination by completing this form.
- Make sure you let us know if you change your address. If we lose touch with you, it can mean you miss out on important information. Email service@ausfoodsuper.com.au
- Have you provided us with your email address? It’s the best way for us to keep you up to date. If you have already provided it, let us know if you change it. Email service@ausfoodsuper.com.au
Could an account-based pension work for you?
If you’ve stopped working or are thinking about retiring, you may want to consider moving some or all of your super from an accumulation account into an account-based pension.
You might consider an account-based pension if you:
- Want to receive regular tax-free income from your super.
- Want your super investments to continue growing in a tax-free environment.
- Are comfortable with investment risk and meeting minimum annual withdrawals.
- Want a relatively simple way to pass remaining super to beneficiaries.
The Australian Food Pension is our account-based pension solution. Open an account or learn more.
What about the Age Pension?
Remember, if you are looking at taking the next step towards retirement, the Age Pension may play an important role in supporting your retirement income. The Age Pension is designed to support eligible Australians in retirement and to qualify, you generally must be:
- 67 years or older
- meet income and assets test requirements
- an Australian resident, usually for at least 10 years
You can learn more about eligibility and apply through Services Australia.
Want to learn more about Social Security?
If you’re interested in learning more about what Centrelink provides around the Age Pension, visit our Retire-Smart Social Security
learning module.
Need Advice?
- Read Take control of your retirement in 8 simple steps for guidance.
- For complex situations, we can connect you with financial advice*. When decisions matter, remember you can always talk to a real person. Our team is ready to help you.
We’re with you for life.
Keep growing your super
If you don’t need to draw an income yet, you may choose to keep your super in an accumulation account so it can continue to grow over time.
You might stay in an accumulation account if you:
- Don’t need income yet and want to keep your super invested for growth.
- Plan to keep contributing to your super.
- Prefer greater flexibility before deciding on a retirement income strategy.
- Are concerned about how market movements could affect pension payments.
- Keeping your account open for insurance cover.
If you have insurance through your super, it’s a good time to review whether it still suits your needs. Depending on your situation, you may choose to keep, adjust or cancel your cover. Reducing or cancelling insurance can mean more of your balance stays invested for your future. Read about all your options here.
Could you add more to your super?
If you’re keeping your account open so it can continue to grow, do you have any opportunities to contribute more money to it? Even small contributions can make a difference over time. Find out more about boosting your retirement savings.
Transition to retirement
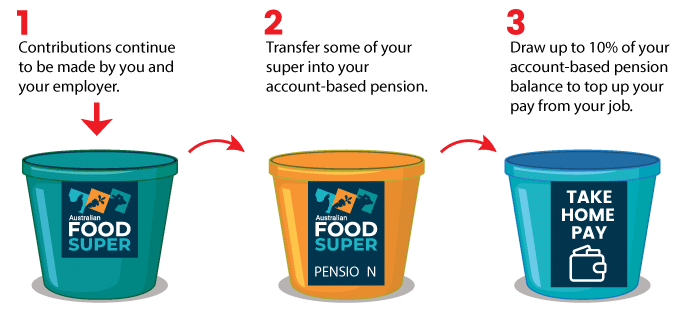
If you’re aged 60 or over and still working, a transition to retirement strategy lets you gradually move from full-time work to retirement.
How it works
- Access a portion of your super through an account-based pension
- Reduce your working hours while supplementing your income
- Potentially lower your tax liability
- Maintain financial stability as you adjust to retirement
TTR pensions have a maximum annual withdrawal limit, and investment earnings are taxed like your Australian Food Super account.
Learn more with Retire-Smart
Learn the basics of preparing for your retirement planning.
The Australian Food Pension is our account-based pension solution. Open an account or learn more here.
Need help with retirement planning?
Even if you already have a plan, it’s always worth reviewing:
- Read Take control of your retirement in 8 simple steps for guidance.
- For complex situations, we can connect you with financial advice*. When decisions matter, remember you can always talk to a real person. Our team is ready to help you.
We’re with you for life.
Could you add more to your super?
Even small contributions can make a difference over time. Depending on your situation, there are several ways you may be able to boost your super and strengthen your retirement savings.
Learn more with our Retire-Smart hub
Learn about building good money habits now and in retirement.
Government co-contributions
You may be eligible for a Government co-contribution when you make personal contributions from your after-tax income:
- If eligible, the Government could add extra money to your super
- This can be a simple way to boost your balance
Contribute a lump sum
If you receive a lump sum—such as an inheritance or proceeds from selling an asset—you may be able to contribute some of it to your super (subject to contribution limits). This could help increase your retirement savings in a tax-effective environment.
Regular contributions
You can also grow your super gradually over time:
- Make personal (after-tax) contributions from your savings
- Consider salary sacrifice if you’re still working, which allows you to contribute before tax
- Your spouse may be able to contribute to your super on your behalf
Even small, regular contributions can add up over time.
See the difference it could make
Want to understand the impact of contributing more?
- Try our Small Change, Big Savings tool, our super calculator that estimates how extra contributions could grow your balance over time
Small Change, Big Savings
Super calculator
How to make a contribution
Making a personal contribution is simple:
- Ask your employer to contribute from your before-tax pay. Please note that some employers do not allow salary sacrifice payments so you will need to check with your payroll.
- Make a contribution directly to your account by BPAY or Electronic Funds Transfer
- Complete a Contribution Form
Or, call us on 1800 808 614 and we can help you get started.
Things to keep in mind
Before making additional contributions, consider:
- Contribution caps apply and exceeding them may result in extra tax
- Eligibility rules may differ depending on your age and work status
- Super is generally a long-term investment and access is limited
Do you have more than one super fund?
If you’ve changed jobs over the years, you may have multiple super accounts—and be paying multiple fees.
You may want to consider consolidating your super into your Australian Food Super account*.
We can help you:
*Before consolidating, check whether you could lose any benefits, such as insurance cover, from your other fund.
What you can do:
- Call us on 1800 808 614
- Roll over online through MemberAccess
- Download and complete a Rollover Form
Low income super tax offset (LISTO)
If you’re a low-income earner, you may benefit from the Government’s Low Income Super Tax Offset (LISTO).
- This scheme helps eligible individuals boost their super
- The Government may refund some of the tax paid on concessional contributions
Learn more about LISTO
We’re here to help
If you’re thinking about adding more to your super, we can help you understand your options and what may be right for you:
- Read Take control of your retirement in 8 simple steps for guidance.
- For complex situations, we can connect you with financial advice*. When decisions matter, remember you can always talk to a real person. Our team is ready to help you.
We’re with you for life.
Is your investment option right for you?
Choosing an investment option that suits your circumstances is an important part of managing your super. As you head toward retirement, keep in mind that it can now last 25-35 years. It’s a good idea to consider whether having some of your savings in higher-risk investments will help support long term income. For example, if you move all your investment to cash, this could increase the risk of running out of money later.
When reviewing your investments, consider:
- Your risk tolerance
If you’re uncomfortable with short-term market fluctuations, a lower-risk option may suit you better. - Your time horizon
Think about how long you have until retirement — and how long your money will need to last in retirement. - Expected returns
Over the long term, higher-risk investments may deliver higher returns, but they also come with more volatility. - Market ups and downs
Investment markets naturally rise and fall.
Our investment options
Australian Food Super offers seven investment options to Pension members:
- Secure
- Capital Stable
- Conservative Balanced
- Balanced
- Growth
- Australian Shares
- International Shares
You can choose to invest in one or spread your investment across two or more options. Please refer to the Investment Guide for more details of these investment options.
Learn about our investment options
Need help?
- Speak to our team on 1800 808 614 if you need some more information. You can also email us at: service@ausfoodsuper.com.au
- If you’d like advice advice at no extra cost to find out what investment strategy is right for you, get in touch here. When decisions matter, remember you can always talk to a real person.