
As you move through your late 40s and 50s, retirement shifts from a distant idea to something much more real. So, if you’re between the ages of 45 and 60 this is your opportunity window – where focused action can significantly improve your retirement outcome.
Here are five smart steps to consider to help turn your super into the lifestyle you want later
Know where you stand
Take a closer look at your super before retirement.
Download the Retirement Readiness checklist now
How much super should I have?
Boost your contributions while you can
Review your investment strategy
Clean up your super
Start planning how you’ll use your super
It’s also a great time to do some housekeeping.
- Check you have nominated your beneficiary(s). And, even if you have, it’s important you make sure that the information is up to date. You can make a beneficiary nomination within the member app or complete this form. You also have the option of making a binding death benefit nomination by completing this form.
- Make sure you let us know if you change your address. If we lose touch with you, it can mean you miss out on important information. Email service@ausfoodsuper.com.au
- Have you provided us with your email address? It’s the best way for us to keep you up to date. If you have already provided it, let us know if you change it. Email service@ausfoodsuper.com.au
How much super should I have?
This is the time to understand what your retirement might look like – and whether your current super balance is on track to support it.
For many people, super balances start to grow more quickly between 45 and 60 as years of contributions and compounding begin to build momentum. At the same time, retirement starts to feel more real, and questions about lifestyle, timing and financial security become more important.
A good first step is to compare your balance with typical super savings for your age and think about the kind of retirement you want. This can help you identify whether you’re on track or whether there may be a gap to address.
The Australian Government’s Moneysmart website offers practical tools and calculators to help answer the common question: “How much super should I have?” and also provides you with average super balances across all age groups. It’s a great place to start when planning ahead. Visit Moneysmart here.
You should also review the projected retirement income estimate included with your Annual Statement. This gives you a snapshot of what your super could provide in retirement, along with any estimated Age Pension entitlement, helping you build a clearer picture of your future income.
The good news? There’s still time to make meaningful progress.
Even small changes now – like reviewing your investment option or making extra contributions – can make a real difference over the next 10 to 15 years.
Get clear with Retire-Smart
If you’re interested in learning more about building good money habits now and in retirement, take a look at our education modules on the Retire-Smart hub, a powerful online resource. Choose a topic and feed your knowledge.
Need Advice?
- Read Take control of your retirement in 8 simple steps for guidance.
- For complex situations, we can connect you with financial advice*.
When decisions matter, remember you can always talk to a real person. Our team is ready to help you.
We’re with you for life.
Make extra contributions
Your peak earning years are a powerful opportunity to grow your super. Extra contributions can be tax-effective and may significantly increase your final balance, especially with compounding over time.
Depending on your situation, there are several ways you may be able to boost your super.
Government co-contributions
You may be eligible for a Government co-contribution when you make personal contributions from your after-tax income:
- If eligible, the Government could add extra money to your super
- This can be a simple way to boost your balance
Regular contributions
You can also grow your super gradually over time:
- Make personal (after-tax) contributions from your savings.
- Consider salary sacrifice if you’re still working, which allows you to contribute before tax.
Even small, regular contributions can add up over time.
Spouse contributions
Many women retire with less super, often due to time out of the workforce to care for family. If your spouse or partner earns a lower income, you may be able to:
- Make an after-tax contribution to their super
- Receive a tax offset of up to $540 if eligibility criteria are met
For example, if your spouse earns less than $37,000, you may receive the maximum offset. This reduces gradually and cuts out at $40,000.
This can be a practical way to support your household’s long-term financial position. You can read more here.
The “Downsizer” measure
Thinking about downsizing? If you’re aged 55 or over and meet the eligibility rules, you may be able to contribute up to $300,000 from the sale of your home into your super (up to $600,000 for couples).
A downsizer contribution can be a useful way to boost your retirement savings because it:
- doesn’t count towards your usual contribution caps
- can be made even if your total super balance is over $2.1 million
- doesn’t require you to buy another home after selling.
A few things to keep in mind:
- You can only use the downsizer contribution rules once, from the sale of one home
- It isn’t tax deductible
- It counts towards your transfer balance cap when moving into retirement phase
- It may affect your Age Pension eligibility.
Eligible for Downsizing?
If you’re considering this option, it’s worth checking the eligibility rules before making a decision. Read more here.
Remember
Before making extra contributions, it’s worth considering:
- Contribution caps and limits
- Your cash flow and short-term needs
- Whether contributions are locked away until retirement
Reading our Contributions Fact Sheet can help you understand the rules and make informed decisions.
See the difference it could make
Want to understand the impact of contributing more?
- Try our Small Change, Big Savings tool, our super calculator that estimates how extra contributions could grow your balance over time
Small Change, Big Savings
Super calculator
How to make a contribution
Making a personal contribution is simple:
- Ask your employer to contribute from your before-tax pay. Please note that some employers do not allow salary sacrifice payments so you will need to check with your payroll.
- Make a contribution directly from your bank account by BPAY or Electronic Funds Transfer.
- Complete a Contribution Form
Email service@ausfoodsuper.com.au for help or call us on 1800 808 614 and we can help you get started.
We’re here to help
If you’re thinking about adding more to your super, we can help you understand your options and what may be right for you:
- Read Take control of your retirement in 8 simple steps for guidance.
- For complex situations, we can connect you with financial advice*. When decisions matter, remember you can always talk to a real person. Our team is ready to help you.
We’re with you for life.
Get your investment mix right.
As retirement gets closer, it’s a good time to check whether your investment option still suits your goals, timeframe and comfort with market ups and downs.
While retirement may still be up to 20 years away depending on where you are on your journey, the choices you make now can have a significant impact on your final balance. Staying invested in growth-focused options may continue to deliver stronger long-term returns, but it’s also natural to start thinking more carefully about how much risk you’re comfortable taking as retirement approaches.
The challenge is finding the right balance.
Moving to a lower-risk option too early could mean missing years of potential growth, which may reduce your retirement savings over time. On the other hand, staying in a higher-risk option without reviewing whether it still suits your circumstances could expose you to more short-term volatility than you’re comfortable with.
This is a good stage of life to ask yourself:
- How many years until I plan to retire?
- Am I comfortable with market fluctuations?
- Does my current investment option match my long-term goals?
- Have my priorities or financial circumstances changed?
Even small adjustments now can make a meaningful difference later. Reviewing your investment strategy regularly helps ensure your super remains aligned with where you are today – and where you want to be in retirement.
Our investment options
You can choose how your super is invested. Australian Food Super offers a range of options. You can select one option or spread your investment across several.
| Lower to medium risk options | Growth-focused options |
| Secure | Growth |
| Capital Stable | Australian Shares |
| Conservative Balanced | International Shares |
| MySuper | |
| Balanced |
If you don’t make a choice, your super is invested in the MySuper option. Please refer to the Investment Guide for more details of these investment options.
Need help choosing?
You can learn more about our investment options here. If you’re unsure what’s right for you:
- Call us on 1800 808 614
- Email service@ausfoodsuper.com.au
- Or access advice about your super at no extra cost to help find an investment strategy that suits your needs.
We’re with you for life.
Clean up your super
It’s important to stay involved in your super, even if you’re confident your investment strategy is matching your goals and you have a contribution plan in place.
Housecleaning
Even simple housekeeping can improve your long-term outcome. Consider:
- A debt reduction plan so that when you do retire, you don’t need to eat into your retirement savings to settle any remaining debt.
- Staying alert to scams
- Keeping your details up to date. Make sure we have your current email address and phone number. You can update your details in the app or send an email to service@ausfoodsuper.com.au
- Have you nominated who your super, and any insurance, would go to if you were to pass away? Update your beneficiaries in the app or complete the Beneficiary Nomination form. You also have the option of making a binding death benefit nomination by completing this form.
- Make sure you check and understand your Annual Statement. A quick annual check-in can make sure your investment option, contributions and details still match your goals.
- You should also review the projected retirement income estimate included with your Annual Statement. This gives you a snapshot of what your super could provide in retirement, along with any estimated Age Pension entitlement, helping you build a clearer picture of your future income. You’ll find your Statement in the tab: Statements/Messages.
- Take the time to understand your insurance cover options and review whether it’s still meeting your needs — you might be paying for cover you don’t need or you might not have enough for your situation.
Got more than one super fund?
If you’ve changed jobs over the years, there’s a good chance you’ve ended up with multiple super accounts. Bringing them together could make managing your money simpler and improve visibility over your total balance – and may help reduce the fees you pay.
Every super account charges its own fees, and you might also be paying for duplicate insurance cover without realising it. Over time, these extra costs can eat into your balance and reduce the benefits of compounding.
Learn more about debt with Retire-Smart
Housekeeping tips
Take action
Check online in MemberAccess, our online account portal:
- Log in to your account
- Go to ‘Consolidate your super’
- Select ‘SuperMatch2 – Search for your super’
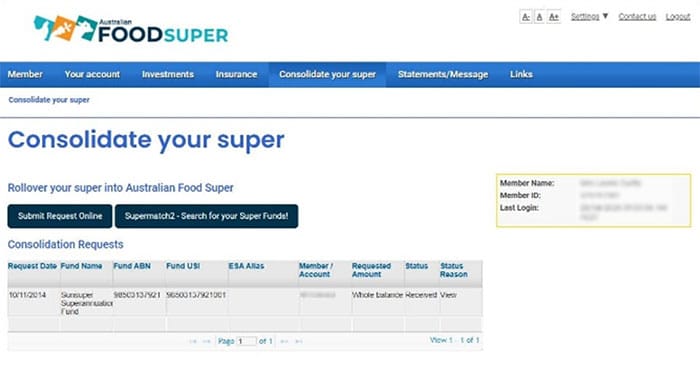
If you’ve provided your Tax File Number and consent to a search, the system will use the ATO website to look for any other super accounts in your name. If any are found, they’ll be displayed and you can choose to roll them into your Australian Food Super account online.
Or let us help. Call us on 1800 808 614 and we can do the search for you and help you combine your accounts.
Before you consolidate: Make sure you check whether you’ll lose any insurance cover when closing an account and consider whether rolling your super into one account is right for you.
Log in to your account and take control of your super today!
Don’t have access to your online account?
If you haven’t registered for MemberAccess or downloaded the member app, read our guide:
What are your plans for retirement?
You don’t have to wait until retirement to think about how your super will work for you and how you will receive an income. From around age 55–60 (your preservation age), you have some options to consider.
Start a transition-to-retirement strategy
If you’re aged 60 or over and still working, a transition to retirement strategy lets you gradually move from full-time work to retirement. A TTR strategy may not suit everyone. Consider getting advice.
Read all the facts in our TTR fact sheet
How it works
- Access a portion of your super through an account-based pension
- Reduce your working hours while supplementing your income
- Potentially lower your tax liability
- Maintain financial stability as you adjust to retirement
TTR pensions have a maximum annual withdrawal limit, and investment earnings are taxed like your Australian Food Super account.
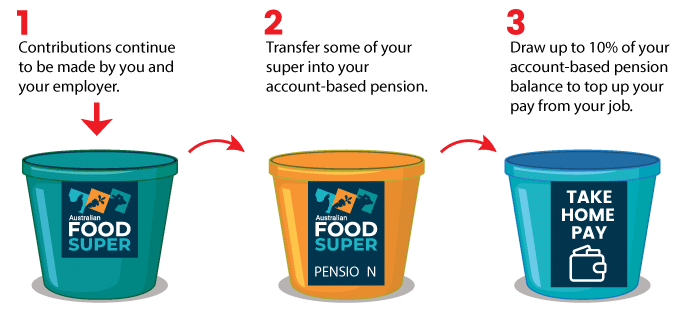
Plan for an income stream in retirement
When you are thinking about retiring, you may want to consider moving some or all of your super from an accumulation account into an account-based pension, turning your super into retirement income.
You might consider an account-based pension if you:
- Want to receive regular tax-free income from your super.
- Want your super investments to continue growing in a tax-free environment.
- Are comfortable with investment risk and meeting minimum annual withdrawals.
- Want a relatively simple way to pass remaining super to beneficiaries.
Australian Food Pension is our account-based pension solution
Open an account or learn more.
What about the Age Pension?
The Age Pension is designed to support eligible Australians in retirement and may complement your super income.
To qualify, you generally must be:
- 67 years or older
- meet income and assets test requirements
- an Australian resident, usually for at least 10 years
You can learn more about eligibility and apply through Services Australia.
Living your dreams
What about your social, hobbies, fitness or travel plans? These are important to consider too. We have some social and health tips for you to consider when planning for retirement — because a fulfilling retirement isn’t just about your finances. Staying socially connected, maintaining good physical and mental health, and building a routine that keeps you active and engaged can all play a big part in enjoying the next stage of life.
Learn more about Social Security
If you’re interested in learning more about what Centrelink provides around the Age Pension, visit our Retire-Smart Social Security
learning module.
Need advice?
Aged 60 or over, withdrawals are generally tax-free if conditions are met, which can play a big role in your overall retirement strategy. Find out more about when you can access your super. Whether this is right for you depends on your personal financial situation, so it’s important to seek advice before making any changes.
- Check out Retire-Smart to learn more about the basics of preparing for your retirement planning.
- Read Take control of your retirement in 8 simple steps for guidance.
- For complex situations, we can connect you with financial advice*. When decisions matter, remember you can always talk to a real person. Our team is ready to help you.